Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
    Retention of seized documents depends on prosecution reliance, with release required where evidentiary necessity is absent.
    Penalty for dealing in confiscable goods requires proof of knowing involvement and a complete evidentiary chain.
    Alternate statutory remedy governs GST assessment challenge, with statutory appeal preserved and limitation objection barred for the permitted filing ...
    Blocked input tax credit cannot satisfy GST appeal pre-deposit while credit restrictions continue, preserving appellate access after corrections.
    Statutory appellate remedy before a functional GST Tribunal displaces writ proceedings while preserving limitation protection for prior litigation.
    Post-decisional hearing for blocked electronic credit ledgers requires reasoned review of disputed input tax credit claims
    Blocked input tax credit cannot fund an appellate pre-deposit while a valid electronic credit ledger restriction continues.
    Electronic credit ledger blocking remains permissible for determined GST recovery despite an interim stay on debiting available credit.
    Interim protection from arrest allowed GST investigation questioning to proceed while requiring appearance before the Investigating Officer.
    GST rectification for patent errors cannot reopen ineligible input tax credit findings; challenges to the original determination remain available.
    Input tax credit apportionment rectification under Section 161 requires correction of SOP-related mistakes by the proper officer.
    Condonation of delay in income-tax appeals permits registration where bona fide departmental processing establishes sufficient cause.
    Priority of registered security interests prevails over unproclaimed, unregistered Income Tax attachments on secured property.
    Satisfaction note timing under section 153C invalidates delayed proceedings against persons other than those searched
    AI-generated fake precedents vitiate penalty adjudication, requiring fresh determination by an independent officer without unreliable legal material.
    Discretionary writ relief for detained baggage jewellery was denied where delay, non-disclosure, and disputed facts required statutory determination.
    Writ jurisdiction cannot bypass customs appellate limits where natural-justice claims require factual determination through the statutory appeal proce...
    Section 110(2) Release Depends on Expiry of the Validly Extended Notice Period, Not Initial Period Alone
    Corporate revival permits changed business objects and land redevelopment where creditor and workmen settlements support public interest.
    IBC overriding effect extinguishes pre-CIRP parallel operation charges when an approved resolution plan discharges corporate debtor liabilities.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Business dependence on regulatory affairs and compliance...

Business Dependence Establishes Associated Enterprise Status; Domestic Tested Party and Fresh Regulatory Affairs Benchmarking Required

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Income Tax September 7, 2026 Case Laws AT
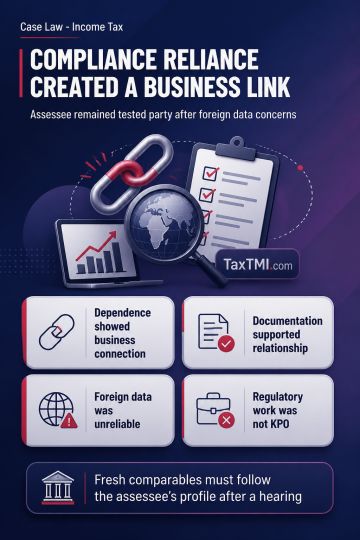
Business dependence on regulatory affairs and compliance processes established an associated-enterprise relationship, which was sustained because the relationship had also been accepted in transfer-pricing documentation. Foreign associated-enterprise selection as the tested party was rejected where reliable foreign comparable data was not readily accessible and geographical and economic conditions differed; the assessee was retained as the tested party. Domain-specific regulatory affairs services were not treated as KPO services merely by reference to the Rule 10TA definition, and comparables from diverse R&D, engineering, IT, advertising and gaming activities were unsuitable. Fresh benchmarking and comparable selection were directed in line with the assessee's FAR profile after a hearing opportunity.

Topics

Acts Income Tax