Restricted second-hand goods remain redeemable when absolute confiscation lacks specific reasons, and penalties must follow the applicable import prov...
Alternate statutory remedy governs GST assessment challenge, with statutory appeal preserved and limitation objection barred for the permitted filing ...
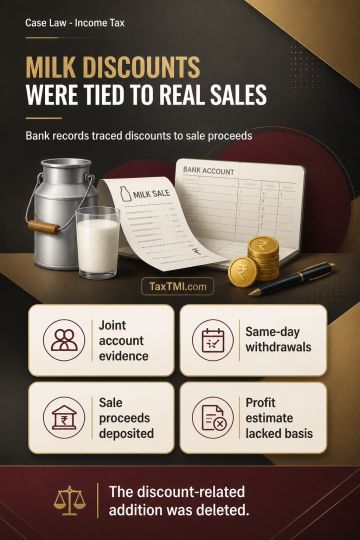
Trade and quantity discounts received by a milk resale agent constituted an explained source of income where bank statements showed that sale proceeds were deposited into a joint account with the dairy and withdrawn by the dairy on the same day. Treating those discounts as unexplained money was therefore unwarranted. Profit estimation at 70% of the total discounts, with only 30% allowed for storage and distribution expenses, lacked a proper basis. The addition relating to the discounts was deleted.
Trade and quantity discounts received by a milk resale agent constituted an explained source of income where bank statements showed that sale proceeds were deposited into a joint account with the dairy and withdrawn by the dairy on the same day. Treating those discounts as unexplained money was therefore unwarranted. Profit estimation at 70% of the total discounts, with only 30% allowed for storage and distribution expenses, lacked a proper basis. The addition relating to the discounts was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4925