Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
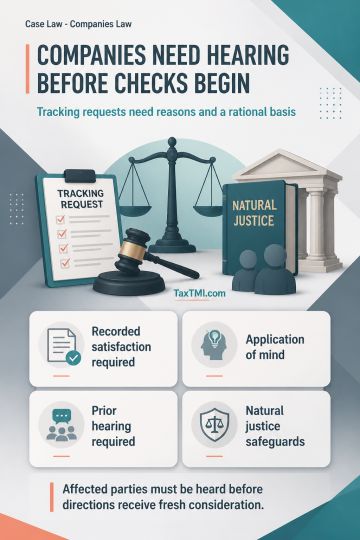
Section 213(b) requires recorded satisfaction, reasons showing application of mind, and a reasonable opportunity of hearing before an investigation into company affairs, or preliminary steps towards it, is directed. Requests to external investigative agencies for tracking information at the initial stage cannot proceed without a rational basis, compliance with those statutory conditions, and prior hearing of affected parties. Directions issued without these safeguards are contrary to natural justice and require fresh consideration after hearing the affected party.
Section 213(b) requires recorded satisfaction, reasons showing application of mind, and a reasonable opportunity of hearing before an investigation into company affairs, or preliminary steps towards it, is directed. Requests to external investigative agencies for tracking information at the initial stage cannot proceed without a rational basis, compliance with those statutory conditions, and prior hearing of affected parties. Directions issued without these safeguards are contrary to natural justice and require fresh consideration after hearing the affected party.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931