Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
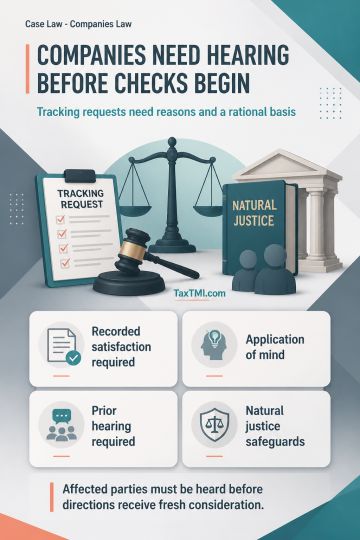
Section 213(b) requires recorded satisfaction, reasons showing application of mind, and a reasonable opportunity of hearing before an investigation into company affairs, or preliminary steps towards it, is directed. Requests to external investigative agencies for tracking information at the initial stage cannot proceed without a rational basis, compliance with those statutory conditions, and prior hearing of affected parties. Directions issued without these safeguards are contrary to natural justice and require fresh consideration after hearing the affected party.
Section 213(b) requires recorded satisfaction, reasons showing application of mind, and a reasonable opportunity of hearing before an investigation into company affairs, or preliminary steps towards it, is directed. Requests to external investigative agencies for tracking information at the initial stage cannot proceed without a rational basis, compliance with those statutory conditions, and prior hearing of affected parties. Directions issued without these safeguards are contrary to natural justice and require fresh consideration after hearing the affected party.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929