Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
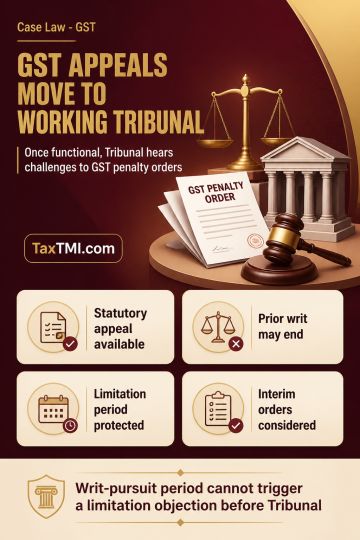
Availability of a statutory appellate remedy before the GST Appellate Tribunal requires a challenge to a GST penalty order to proceed through that forum once it becomes functional. A writ petition entertained solely because the appellate forum was non-functional need not continue after the Tribunal is operational. The petitioner may be relegated to the Tribunal with liberty to file an appeal within the stipulated period, and the Tribunal should not object to limitation for the period during which the writ petition was pursued. The appeal is to be decided in accordance with law after considering any interim order.
Availability of a statutory appellate remedy before the GST Appellate Tribunal requires a challenge to a GST penalty order to proceed through that forum once it becomes functional. A writ petition entertained solely because the appellate forum was non-functional need not continue after the Tribunal is operational. The petitioner may be relegated to the Tribunal with liberty to file an appeal within the stipulated period, and the Tribunal should not object to limitation for the period during which the writ petition was pursued. The appeal is to be decided in accordance with law after considering any interim order.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894