Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
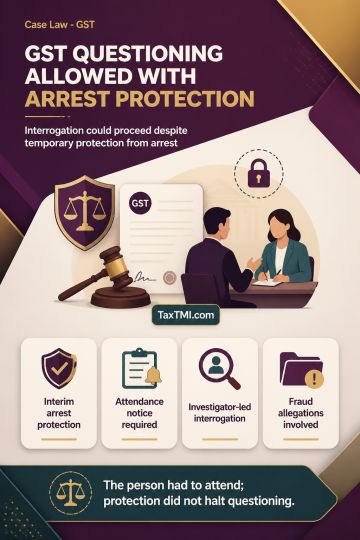
Interim protection from arrest during a GST investigation was granted to a person summoned in connection with alleged GST and input tax credit fraud. The investigating side confirmed that the relevant notices required attendance for interrogation and did not authorise arrest. The person was therefore directed to appear before the Investigating Officer in accordance with the notices, while receiving protection from arrest in the related criminal proceedings. The protection was limited to facilitating interrogation under the issued notices.
Interim protection from arrest during a GST investigation was granted to a person summoned in connection with alleged GST and input tax credit fraud. The investigating side confirmed that the relevant notices required attendance for interrogation and did not authorise arrest. The person was therefore directed to appear before the Investigating Officer in accordance with the notices, while receiving protection from arrest in the related criminal proceedings. The protection was limited to facilitating interrogation under the issued notices.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4884