ODR arbitration participation remains mandatory after failed conciliation, while jurisdictional and maintainability objections stay available before t...
Transparency in technical bid evaluation requires disclosed standards and recorded reasons; opaque scoring invalidated tender awards and required fres...
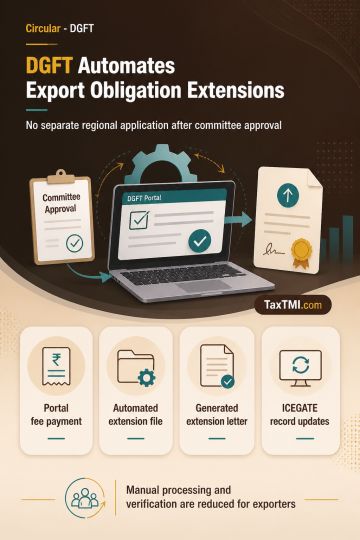
Automated export obligation extensions remove separate regional applications after committee approval for Advance Authorisation and EPCG authorisation...
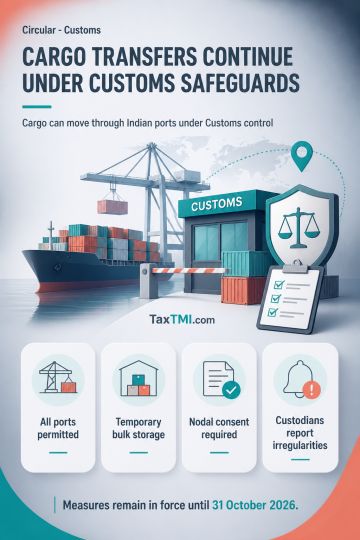
International cargo transhipment through Indian ports continues with Customs-controlled storage, re-export safeguards, and coordinated multi-station m...
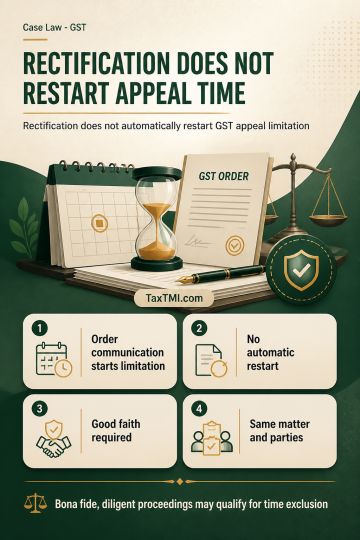
Rectification of patent errors in GST proceedings is confined to errors apparent on the face of the record and cannot be used to revisit an original determination on under-declared ineligible input tax credit. Where no apparent error is established and supporting documents were not submitted, rejection of a rectification application remains undisturbed. The taxpayer may challenge the original determination independently in accordance with law, rather than seek substantive reconsideration through rectification.
Rectification of patent errors in GST proceedings is confined to errors apparent on the face of the record and cannot be used to revisit an original determination on under-declared ineligible input tax credit. Where no apparent error is established and supporting documents were not submitted, rejection of a rectification application remains undisturbed. The taxpayer may challenge the original determination independently in accordance with law, rather than seek substantive reconsideration through rectification.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897