Educational approval requires mandatory State registration, but incidental surplus and trustee-owned land do not prove private benefit or profit motiv...
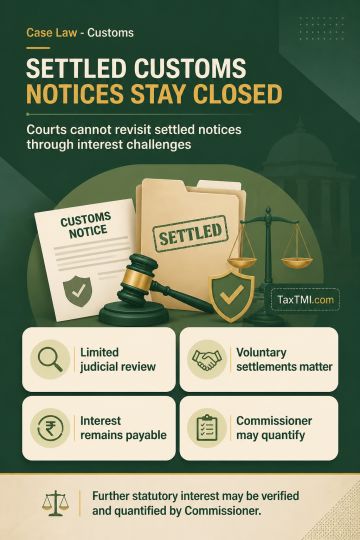
Judicial review of settlement orders cannot reopen settled customs notices, while statutory interest remains subject to verification and quantificatio...
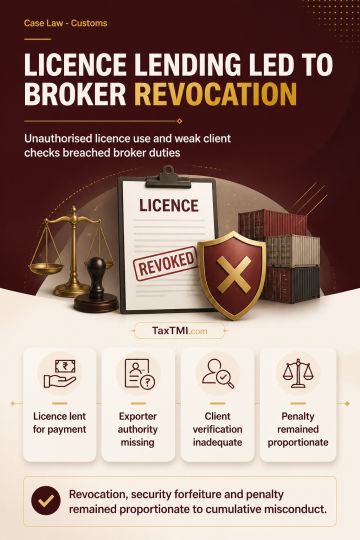
Customs Broker licence lending for consideration justified revocation where exporter authorisation and client verification obligations were also breac...
Rectification of patent errors in GST proceedings is confined to errors apparent on the face of the record and cannot be used to revisit an original determination on under-declared ineligible input tax credit. Where no apparent error is established and supporting documents were not submitted, rejection of a rectification application remains undisturbed. The taxpayer may challenge the original determination independently in accordance with law, rather than seek substantive reconsideration through rectification.
Rectification of patent errors in GST proceedings is confined to errors apparent on the face of the record and cannot be used to revisit an original determination on under-declared ineligible input tax credit. Where no apparent error is established and supporting documents were not submitted, rejection of a rectification application remains undisturbed. The taxpayer may challenge the original determination independently in accordance with law, rather than seek substantive reconsideration through rectification.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894