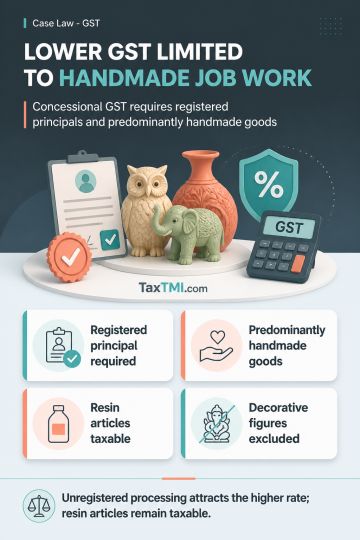
Handicraft job work receives concessional GST only for registered principals and predominantly handmade goods; commercial resin articles remain taxabl...
Reassessment disclosure requirements permit stated reasons without revealing information sources, but prior-taxation claims require full examination b...
Independent assessment discretion and corroborated electronic evidence determine validity of on-money additions and undisclosed-consideration assessme...
Rectification of patent errors in GST proceedings is confined to errors apparent on the face of the record and cannot be used to revisit an original determination on under-declared ineligible input tax credit. Where no apparent error is established and supporting documents were not submitted, rejection of a rectification application remains undisturbed. The taxpayer may challenge the original determination independently in accordance with law, rather than seek substantive reconsideration through rectification.
Rectification of patent errors in GST proceedings is confined to errors apparent on the face of the record and cannot be used to revisit an original determination on under-declared ineligible input tax credit. Where no apparent error is established and supporting documents were not submitted, rejection of a rectification application remains undisturbed. The taxpayer may challenge the original determination independently in accordance with law, rather than seek substantive reconsideration through rectification.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888