Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adju...
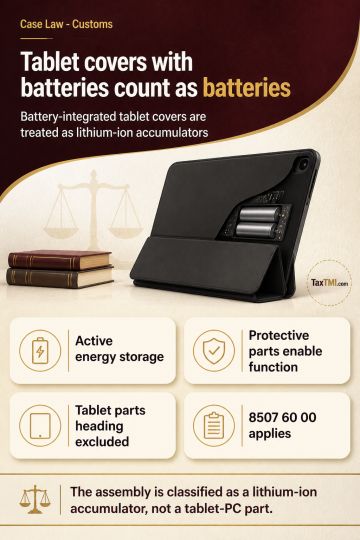
Battery-integrated tablet rear covers classify as lithium-ion accumulators when protective components enable the battery's active energy-storage funct...
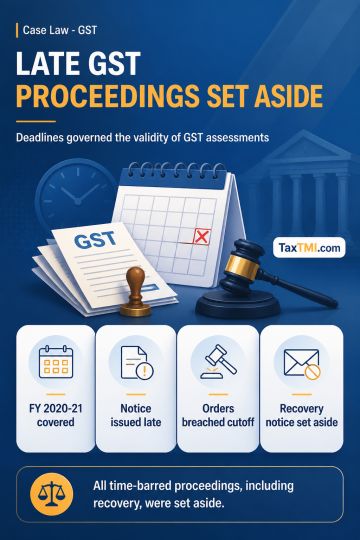
Statutory limitation under Section 73(2) of the Telangana GST Act governed the validity of the show-cause notice and assessment orders for financial year 2020-21. Issuance of the notice after the prescribed deadline, followed by assessment orders beyond the applicable cut-off, constituted a jurisdictional error. The time-barred proceedings, including the consequential recovery notice, were therefore set aside.
Statutory limitation under Section 73(2) of the Telangana GST Act governed the validity of the show-cause notice and assessment orders for financial year 2020-21. Issuance of the notice after the prescribed deadline, followed by assessment orders beyond the applicable cut-off, constituted a jurisdictional error. The time-barred proceedings, including the consequential recovery notice, were therefore set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891