Restricted second-hand goods remain redeemable when absolute confiscation lacks specific reasons, and penalties must follow the applicable import prov...
Alternate statutory remedy governs GST assessment challenge, with statutory appeal preserved and limitation objection barred for the permitted filing ...
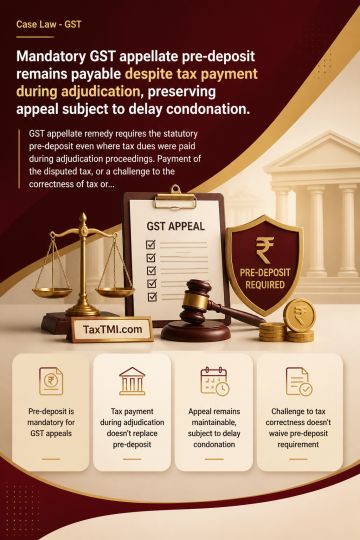
GST appellate remedy requires the statutory pre-deposit even where tax dues were paid during adjudication proceedings. Payment of the disputed tax, or a challenge to the correctness of tax or penalty, does not dispense with this filing condition; those issues must be determined on the appeal's merits. The petitioner could pursue the statutory appeal only after making the prescribed deposit and filing a delay-condonation application. The appellate authority was directed to consider the delay application sympathetically and, if satisfied, decide the appeal on merits.
GST appellate remedy requires the statutory pre-deposit even where tax dues were paid during adjudication proceedings. Payment of the disputed tax, or a challenge to the correctness of tax or penalty, does not dispense with this filing condition; those issues must be determined on the appeal's merits. The petitioner could pursue the statutory appeal only after making the prescribed deposit and filing a delay-condonation application. The appellate authority was directed to consider the delay application sympathetically and, if satisfied, decide the appeal on merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4883