Reassessment sanction under extended limitation required approval from the competent specified authority, invalidating proceedings approved by an inco...
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
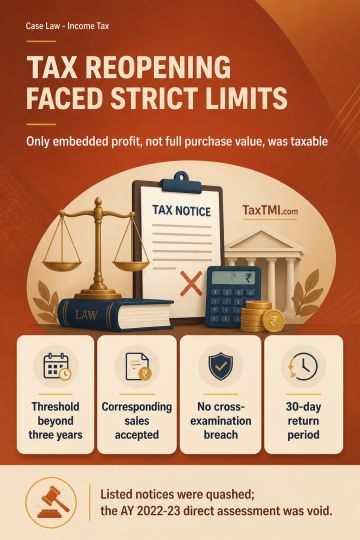
Reassessment beyond three years requires escaped income to meet the statutory threshold; where unaccounted purchases had corresponding sales and the embedded profit was separately assessed, only that profit constituted escaped income. Reassessment notices for AY 2014-15 to AY 2018-19 were therefore quashed. Material seized during a third-party search required notice under section 148 before assessment, rendering the direct AY 2022-23 assessment void. No cross-examination breach arose without a specific request, and the pre-amendment reassessment regime permitted a 30-day return period. Where corresponding sales were accepted, tax applied only to embedded profit, not the full unaccounted purchase value.
Reassessment beyond three years requires escaped income to meet the statutory threshold; where unaccounted purchases had corresponding sales and the embedded profit was separately assessed, only that profit constituted escaped income. Reassessment notices for AY 2014-15 to AY 2018-19 were therefore quashed. Material seized during a third-party search required notice under section 148 before assessment, rendering the direct AY 2022-23 assessment void. No cross-examination breach arose without a specific request, and the pre-amendment reassessment regime permitted a 30-day return period. Where corresponding sales were accepted, tax applied only to embedded profit, not the full unaccounted purchase value.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4883