Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
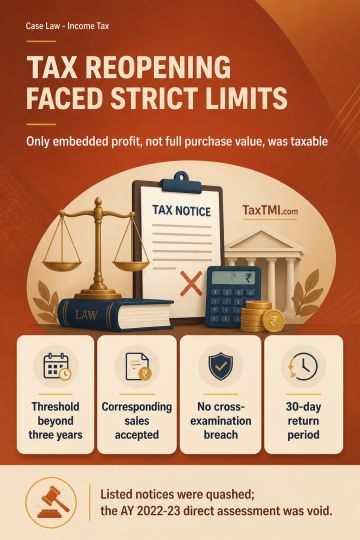
Reassessment beyond three years requires escaped income to meet the statutory threshold; where unaccounted purchases had corresponding sales and the embedded profit was separately assessed, only that profit constituted escaped income. Reassessment notices for AY 2014-15 to AY 2018-19 were therefore quashed. Material seized during a third-party search required notice under section 148 before assessment, rendering the direct AY 2022-23 assessment void. No cross-examination breach arose without a specific request, and the pre-amendment reassessment regime permitted a 30-day return period. Where corresponding sales were accepted, tax applied only to embedded profit, not the full unaccounted purchase value.
Reassessment beyond three years requires escaped income to meet the statutory threshold; where unaccounted purchases had corresponding sales and the embedded profit was separately assessed, only that profit constituted escaped income. Reassessment notices for AY 2014-15 to AY 2018-19 were therefore quashed. Material seized during a third-party search required notice under section 148 before assessment, rendering the direct AY 2022-23 assessment void. No cross-examination breach arose without a specific request, and the pre-amendment reassessment regime permitted a 30-day return period. Where corresponding sales were accepted, tax applied only to embedded profit, not the full unaccounted purchase value.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888