Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party...
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
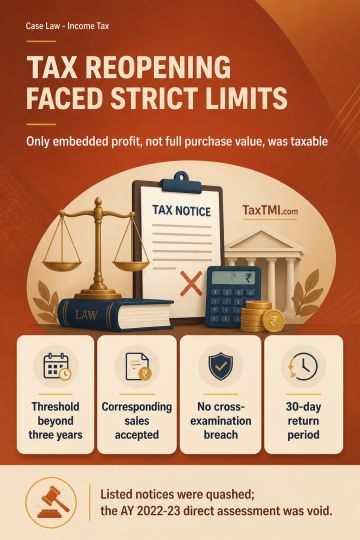
Reassessment beyond three years requires escaped income to meet the statutory threshold; where unaccounted purchases had corresponding sales and the embedded profit was separately assessed, only that profit constituted escaped income. Reassessment notices for AY 2014-15 to AY 2018-19 were therefore quashed. Material seized during a third-party search required notice under section 148 before assessment, rendering the direct AY 2022-23 assessment void. No cross-examination breach arose without a specific request, and the pre-amendment reassessment regime permitted a 30-day return period. Where corresponding sales were accepted, tax applied only to embedded profit, not the full unaccounted purchase value.
Reassessment beyond three years requires escaped income to meet the statutory threshold; where unaccounted purchases had corresponding sales and the embedded profit was separately assessed, only that profit constituted escaped income. Reassessment notices for AY 2014-15 to AY 2018-19 were therefore quashed. Material seized during a third-party search required notice under section 148 before assessment, rendering the direct AY 2022-23 assessment void. No cross-examination breach arose without a specific request, and the pre-amendment reassessment regime permitted a 30-day return period. Where corresponding sales were accepted, tax applied only to embedded profit, not the full unaccounted purchase value.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888