E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
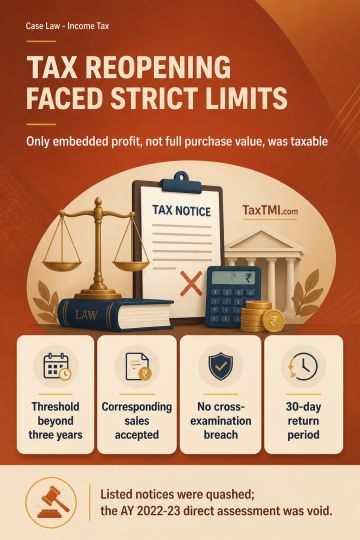
Reassessment beyond three years requires escaped income to meet the statutory threshold; where unaccounted purchases had corresponding sales and the embedded profit was separately assessed, only that profit constituted escaped income. Reassessment notices for AY 2014-15 to AY 2018-19 were therefore quashed. Material seized during a third-party search required notice under section 148 before assessment, rendering the direct AY 2022-23 assessment void. No cross-examination breach arose without a specific request, and the pre-amendment reassessment regime permitted a 30-day return period. Where corresponding sales were accepted, tax applied only to embedded profit, not the full unaccounted purchase value.
Reassessment beyond three years requires escaped income to meet the statutory threshold; where unaccounted purchases had corresponding sales and the embedded profit was separately assessed, only that profit constituted escaped income. Reassessment notices for AY 2014-15 to AY 2018-19 were therefore quashed. Material seized during a third-party search required notice under section 148 before assessment, rendering the direct AY 2022-23 assessment void. No cross-examination breach arose without a specific request, and the pre-amendment reassessment regime permitted a 30-day return period. Where corresponding sales were accepted, tax applied only to embedded profit, not the full unaccounted purchase value.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891