Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
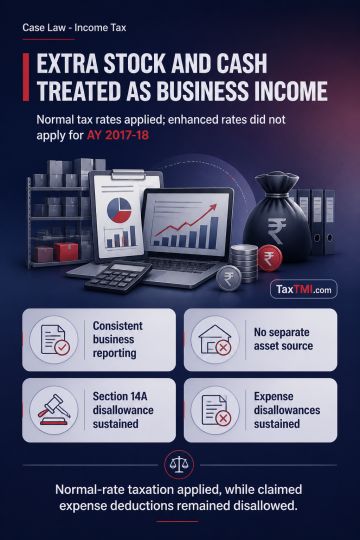
Surrendered excess stock and cash identified during a survey were characterised as business income where the taxpayer consistently offered them as miscellaneous business income, dealt regularly in the excess stock, and had no independent undisclosed asset or non-business income source. Such income was therefore taxable at normal rates. The enhanced rate introduced under section 115BBE applied prospectively from Financial Year 2017-18, corresponding to AY 2018-19, and did not apply to AY 2017-18. Disallowance of investment-related expenditure under section 14A was sustained as statutorily computed, and ad hoc disallowances of specified business expenses were also sustained where ledger extracts and cash payments did not justify interference.
Surrendered excess stock and cash identified during a survey were characterised as business income where the taxpayer consistently offered them as miscellaneous business income, dealt regularly in the excess stock, and had no independent undisclosed asset or non-business income source. Such income was therefore taxable at normal rates. The enhanced rate introduced under section 115BBE applied prospectively from Financial Year 2017-18, corresponding to AY 2018-19, and did not apply to AY 2017-18. Disallowance of investment-related expenditure under section 14A was sustained as statutorily computed, and ad hoc disallowances of specified business expenses were also sustained where ledger extracts and cash payments did not justify interference.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894