Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Questions arising from miscellaneous application orders cannot challenge unaltered Tribunal findings, leaving the original order separately challengea...
Transfer-pricing comparability filters require fresh arm's-length analysis, while delayed receivables need separate reconsideration with working-capit...
Page of 4896
Press 'Enter' after typing page number.
761 to 780 of 97907 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
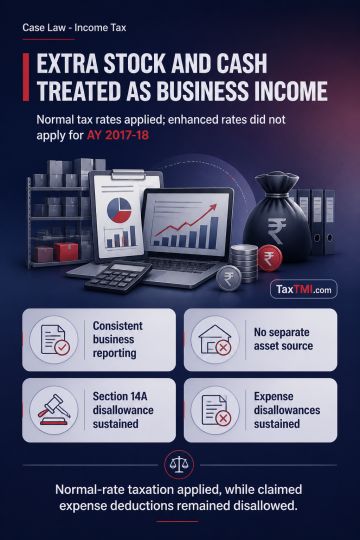
Surrendered excess stock and cash identified during a survey were characterised as business income where the taxpayer consistently offered them as miscellaneous business income, dealt regularly in the excess stock, and had no independent undisclosed asset or non-business income source. Such income was therefore taxable at normal rates. The enhanced rate introduced under section 115BBE applied prospectively from Financial Year 2017-18, corresponding to AY 2018-19, and did not apply to AY 2017-18. Disallowance of investment-related expenditure under section 14A was sustained as statutorily computed, and ad hoc disallowances of specified business expenses were also sustained where ledger extracts and cash payments did not justify interference.
Surrendered excess stock and cash identified during a survey were characterised as business income where the taxpayer consistently offered them as miscellaneous business income, dealt regularly in the excess stock, and had no independent undisclosed asset or non-business income source. Such income was therefore taxable at normal rates. The enhanced rate introduced under section 115BBE applied prospectively from Financial Year 2017-18, corresponding to AY 2018-19, and did not apply to AY 2017-18. Disallowance of investment-related expenditure under section 14A was sustained as statutorily computed, and ad hoc disallowances of specified business expenses were also sustained where ledger extracts and cash payments did not justify interference.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896