Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
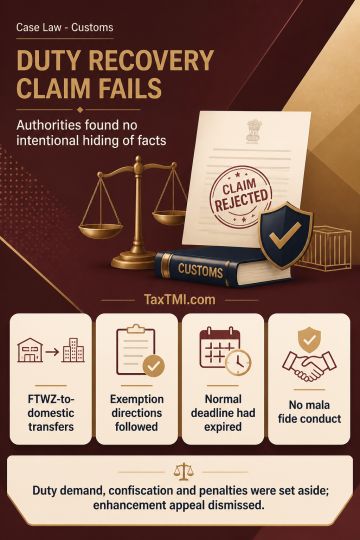
Extended limitation could not support recovery of Special Additional Duty on goods transferred from an FTWZ to a domestic tariff area unit because the exemption practice followed directions and decisions of SEZ and FTWZ authorities, including a chartered accountant's certificate. The Tribunal found no mala fides or suppression of facts intended to evade duty. As the entire demand lay outside the normal limitation period, the extended period was unavailable and the exemption's merits required no examination. The duty demand, confiscation and penalties were set aside, and Revenue's penalty-enhancement appeal was dismissed.
Extended limitation could not support recovery of Special Additional Duty on goods transferred from an FTWZ to a domestic tariff area unit because the exemption practice followed directions and decisions of SEZ and FTWZ authorities, including a chartered accountant's certificate. The Tribunal found no mala fides or suppression of facts intended to evade duty. As the entire demand lay outside the normal limitation period, the extended period was unavailable and the exemption's merits required no examination. The duty demand, confiscation and penalties were set aside, and Revenue's penalty-enhancement appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886