E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
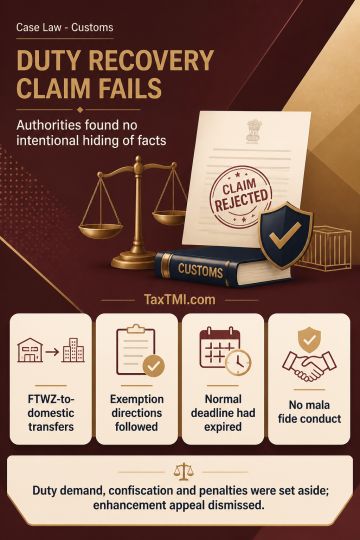
Extended limitation could not support recovery of Special Additional Duty on goods transferred from an FTWZ to a domestic tariff area unit because the exemption practice followed directions and decisions of SEZ and FTWZ authorities, including a chartered accountant's certificate. The Tribunal found no mala fides or suppression of facts intended to evade duty. As the entire demand lay outside the normal limitation period, the extended period was unavailable and the exemption's merits required no examination. The duty demand, confiscation and penalties were set aside, and Revenue's penalty-enhancement appeal was dismissed.
Extended limitation could not support recovery of Special Additional Duty on goods transferred from an FTWZ to a domestic tariff area unit because the exemption practice followed directions and decisions of SEZ and FTWZ authorities, including a chartered accountant's certificate. The Tribunal found no mala fides or suppression of facts intended to evade duty. As the entire demand lay outside the normal limitation period, the extended period was unavailable and the exemption's merits required no examination. The duty demand, confiscation and penalties were set aside, and Revenue's penalty-enhancement appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891