Effective hearing in GST adjudication requires actual opportunity to respond; ineffective service through a former auditor invalidated ex parte procee...
Third-party search material requires special assessment route, rendering general reassessment notices without jurisdiction when it forms the proceedin...
Transfer-pricing adjustments must be confined to international associated-enterprise transactions, while functionally dissimilar comparables remain ex...
Insolvency moratorium bars income-tax revision proceedings against corporate debtors until the moratorium ends, preserving merits for later determinat...
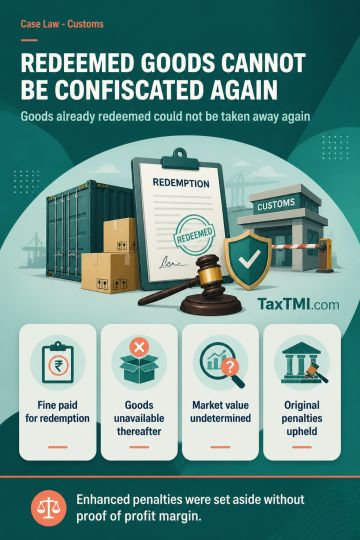
Absolute confiscation of imported computer hard discs was set aside because the goods had already been redeemed on payment of fine and were unavailable for further redemption; the confiscation merits had attained finality. Reliance on Supreme Court precedent supporting redemption meant that a subsequent absolute-confiscation direction was non-est in law. Enhanced penalties on the importer and its business head were also set aside because the original penalties were proportionate to the offence and market value had not been determined to establish the profit margin. The adjudication order allowing redemption and imposing the original penalties was sustained.
Absolute confiscation of imported computer hard discs was set aside because the goods had already been redeemed on payment of fine and were unavailable for further redemption; the confiscation merits had attained finality. Reliance on Supreme Court precedent supporting redemption meant that a subsequent absolute-confiscation direction was non-est in law. Enhanced penalties on the importer and its business head were also set aside because the original penalties were proportionate to the offence and market value had not been determined to establish the profit margin. The adjudication order allowing redemption and imposing the original penalties was sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886