Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
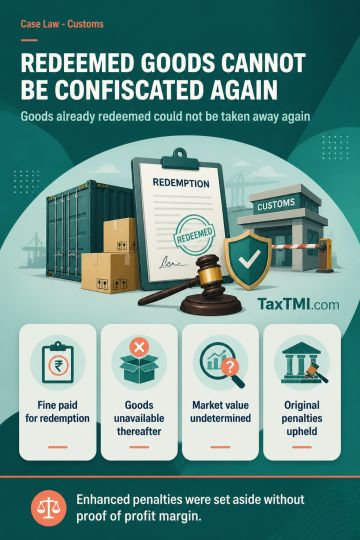
Absolute confiscation of imported computer hard discs was set aside because the goods had already been redeemed on payment of fine and were unavailable for further redemption; the confiscation merits had attained finality. Reliance on Supreme Court precedent supporting redemption meant that a subsequent absolute-confiscation direction was non-est in law. Enhanced penalties on the importer and its business head were also set aside because the original penalties were proportionate to the offence and market value had not been determined to establish the profit margin. The adjudication order allowing redemption and imposing the original penalties was sustained.
Absolute confiscation of imported computer hard discs was set aside because the goods had already been redeemed on payment of fine and were unavailable for further redemption; the confiscation merits had attained finality. Reliance on Supreme Court precedent supporting redemption meant that a subsequent absolute-confiscation direction was non-est in law. Enhanced penalties on the importer and its business head were also set aside because the original penalties were proportionate to the offence and market value had not been determined to establish the profit margin. The adjudication order allowing redemption and imposing the original penalties was sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891