Year-wise GST tax periods make composite show cause notices impermissible, requiring separate proceedings despite contrary non-jurisdictional preceden...
Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adju...
Page of 4888
Press 'Enter' after typing page number.
821 to 840 of 97755 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
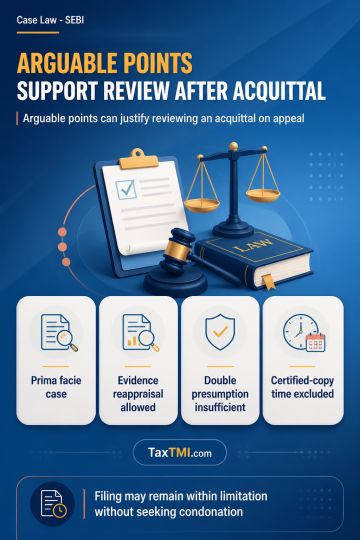
Leave to appeal against an acquittal requires the Court to determine whether a prima facie case or arguable points warrant examination. It need not minutely evaluate evidence or conclusively decide whether the acquittal is perverse at that stage. Where the record requires reappreciation, review or reconsideration of evidence, leave should be granted and merits considered in the criminal appeal; the double presumption of innocence does not itself justify refusing leave. For limitation, time spent processing and obtaining a certified copy of the impugned judgment is excluded, and the effective filing period may therefore fall within the prescribed limit without condonation.
Leave to appeal against an acquittal requires the Court to determine whether a prima facie case or arguable points warrant examination. It need not minutely evaluate evidence or conclusively decide whether the acquittal is perverse at that stage. Where the record requires reappreciation, review or reconsideration of evidence, leave should be granted and merits considered in the criminal appeal; the double presumption of innocence does not itself justify refusing leave. For limitation, time spent processing and obtaining a certified copy of the impugned judgment is excluded, and the effective filing period may therefore fall within the prescribed limit without condonation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888