Transfer-pricing treatment of ITeS margins excludes pass-through tax recoveries and separate delayed-receivables interest after working-capital adjust...
Capacity-utilisation adjustments under TNMM can neutralise substantiated COVID-related idle costs where underutilisation materially affects profitabil...
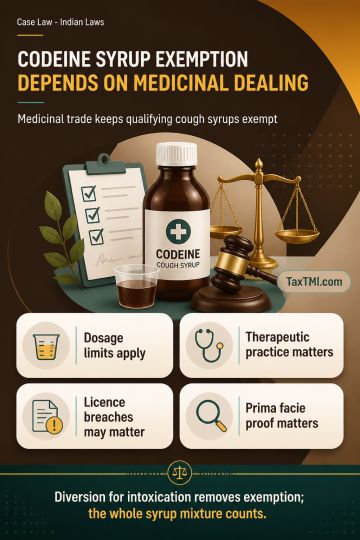
Entry 35 exempts codeine cough-syrup preparations compounded within prescribed dosage and concentration limits and established in therapeutic practice when dealt with in the ordinary course of medicinal business. Routine sales without prescription or ordinary licence breaches ordinarily attract action under the Drugs and Cosmetics Act unless non-medicinal diversion is established; licence-condition breaches involving narcotic drugs may also permit NDPS prosecution. Diversion for intoxication removes the exemption and renders the preparation a manufactured drug, with the entire syrup mixture relevant to quantity assessment. Regular bail depends on prima facie proof of conscious possession, trafficking, conspiracy, or diversion; sealed consignments, mere employment, or uncorroborated allegations may be insufficient.
Entry 35 exempts codeine cough-syrup preparations compounded within prescribed dosage and concentration limits and established in therapeutic practice when dealt with in the ordinary course of medicinal business. Routine sales without prescription or ordinary licence breaches ordinarily attract action under the Drugs and Cosmetics Act unless non-medicinal diversion is established; licence-condition breaches involving narcotic drugs may also permit NDPS prosecution. Diversion for intoxication removes the exemption and renders the preparation a manufactured drug, with the entire syrup mixture relevant to quantity assessment. Regular bail depends on prima facie proof of conscious possession, trafficking, conspiracy, or diversion; sealed consignments, mere employment, or uncorroborated allegations may be insufficient.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894