Charitable trust registration requires a specified-violation notice; settled cash deposits and related-party payments did not justify cancellation or ...
External development charges trigger TDS under section 194C, while disputed administrative payments require factual verification and fresh adjudicatio...
Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
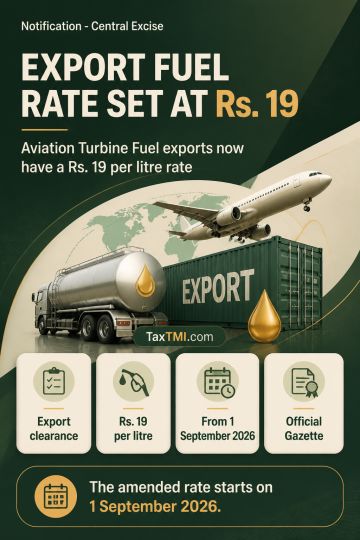
The effective rate of Special Additional Excise Duty on Aviation Turbine Fuel cleared for export is amended to Rs. 19 per litre by substituting the entry against serial number 1 in Notification No. 08/2026-Central Excise. The revised rate takes effect from 1 September 2026, the date of publication in the Official Gazette.
The effective rate of Special Additional Excise Duty on Aviation Turbine Fuel cleared for export is amended to Rs. 19 per litre by substituting the entry against serial number 1 in Notification No. 08/2026-Central Excise. The revised rate takes effect from 1 September 2026, the date of publication in the Official Gazette.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886