Concessional corporate tax option under section 115BAA survives procedural documentary lapses when statutory compliance and earlier exercise are estab...
Penny-stock additions require transaction-specific evidence; general investigation material alone cannot establish undisclosed income or accommodation...
Transfer pricing comparability prioritises reliable external CUPs and foreign-currency LIBOR benchmarks for exports, borrowings and delayed receivable...
Section 153C satisfaction and seized electronic records sustained unexplained-investment addition, subject to proportionate ownership-share verificati...
Page of 4888
Press 'Enter' after typing page number.
1501 to 1520 of 97750 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
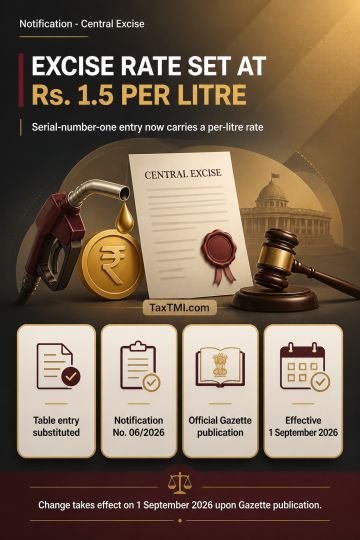
The central excise rate entry at serial number 1, column (4), under Notification No. 06/2026-Central Excise is substituted with "Rs. 1.5 per litre". The amendment changes that table entry and takes effect on 1 September 2026, the date of publication in the Official Gazette.
Note: It is a system-generated summary and is for quick reference only.