Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Conditional aircraft duty exemptions fail when commercial charter operations lack required regulatory authorisation, triggering confiscation, duty rec...
    Statutory penalty ceiling under cargo handling regulations restricts sanctions to the prescribed maximum for customs-area cargo operators.
    Prospective import-policy amendments cannot impose new Actual User registration conditions on earlier warehoused newsprint imports.
    Social Welfare Surcharge exemption follows when imported PET coke receives basic customs duty exemption through MEIS duty credit scrips.
    Without-prejudice insolvency deposits cannot replace adjudication of debt, default, and maintainability in Section 7 proceedings.
    Resolution applicant death does not automatically justify liquidation; viable plan implementation and pending CIRP withdrawal require consideration.
    Clean slate protection in liquidation preserves Section 32A immunity, while statutory waivers require recourse to relevant authorities.
    Equivalent-asset seizure under FEMA covers continuing undisclosed foreign exchange holdings despite retrospective-application and residential-status o...
    Equivalent-value attachment survives prior release and environmental compensation where deposits may represent proceeds from alleged illegal mining ac...
    Provisional attachment of alleged crime proceeds continues where inflated share-sale gains may reflect layered bribe funds.
    Leasehold land transfers for approved SEZ units qualify for fiscal incentives despite execution before implementing legislation.
    GST reimbursement for ongoing works survives tender rates limited to taxes applicable at bidding, despite conflicting pre-bid clarifications.
    Standard deficiency memo format mandated for Section 74 drawback claims to ensure uniform, transparent and timely processing.
    Brand Rate of Drawback processing requires risk-based verification, checklist scrutiny, and Commissioner approval for final rate determination.
    Section 49 storage facilitation requires early importer notice, expedited decisions, and verified detention or demurrage waiver certificates.
    Import container scanning exclusions remove routine screening for empty imports and international transshipment cargo unless intelligence prompts exam...
    Partial Customs Area de-notification confines CFS custodianship and cargo service approval to the retained operational premises.
    Withdrawal of obsolete FEMA circulars streamlines rules on external commercial borrowings, non-resident bond investments, and money transfer sub-agent...
    Standard Input Output Norm suspension proposed for unused norms, with stakeholders invited to substantiate continued scheme utilisation.
    Section 61 return scrutiny is not mandatory before fraud-based input tax credit proceedings, leaving factual invoice disputes for adjudication.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Taxpayer confidentiality bars officers and staff from...

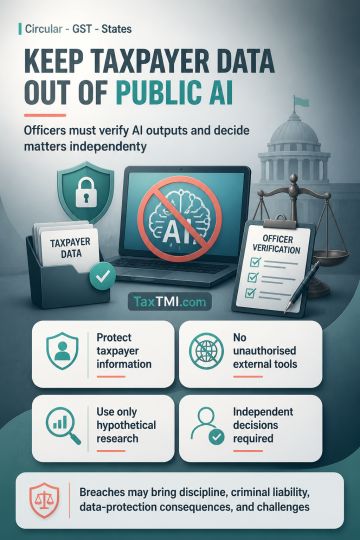
Taxpayer confidentiality restricts external AI use while requiring officers to verify outputs and independently decide quasi-judicial matters.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

GST - States September 2, 2026 Circulars
Taxpayer confidentiality bars officers and staff from transmitting identifiable taxpayer information or departmental data to public or commercial AI tools, third-party online platforms, external systems, browser extensions or personal accounts unless expressly authorised in writing. Permitted AI use is limited to generic, wholly hypothetical legal or procedural research and drafting support, with independent verification against primary sources. Officers remain personally responsible for disclosures made by themselves or persons acting under their control; breaches may lead to disciplinary action, criminal liability, data-protection consequences and challenges to affected proceedings. Notices and quasi-judicial orders must reflect the signing officer's independent assessment of facts and law, not unverified or mechanically adopted AI-generated content.

Topics

Acts Income Tax