Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Resolution-plan finality extinguishes unsubmitted statutory dues and prevents recovery of pre-approval electricity-duty and mining demands.
    Substitution of attached property by fixed deposit remains discretionary, while statutory PMLA appeals ordinarily preclude writ intervention.
    Attachment of proceeds of crime can reach equivalent-value property, pre-offence assets, and property held by persons outside the predicate offence.
    Provisional attachment of officials' properties sustained where evidence linked them to diverted proceeds of unlawful investment schemes.
    Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
    Excise assessment at removal protects PDS kerosene from duty claims on post-clearance pipeline interface formation.
    Unauthorised occupation status cannot arise solely from unresolved lease transfer and prior dues after a secured creditor auction.
    Automated Free Sale and Commerce Certificates enable paperless processing while retaining risk-based manual verification for selected exporter applica...
    Statutory GST appellate limitation cannot ordinarily be bypassed through writ jurisdiction after it has expired following unexplained delay.
    Omitted export-refund restriction cannot govern pending integrated-tax refund proceedings without an express saving or sunset clause.
    Arrest safeguards under the CGST Act support regular bail where recorded reasons and statutory thresholds are absent.
    Rule 86A credit restrictions require recorded written reasons; non-compliant ledger blocking may trigger compensation liability.
    Employee stock-shortage penalties do not constitute consideration for services, preventing GST collection under Schedule II in employment relationship...
    Consolidated show-cause notices may cover multiple years, but appellate authorities must provide a meaningful hearing on merits.
    Statutory appellate remedy bars delayed writ challenge to GST registration cancellation absent exceptional circumstances, preserving fresh registratio...
    Fresh adjudication on contractual material requires reconsideration of service-tax demand and exemption claim after a hearing.
    Parallel GST proceedings on identical issues were invalid after Central GST adjudication for the same assessment period.
    Premature tax assessment before the annual-return deadline is invalid, requiring fresh proceedings with notice and hearing.
    Incorrect GST head payment: clerical IGST remittance can be adjusted against CGST and SGST without interest or penalty.
    Revisional relief for omitted charitable-trust capital-gains claims extends to fixed-deposit reinvestment where disclosure was complete.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Money Laundering

Under the Prevention of Money Laundering Act, provisional...

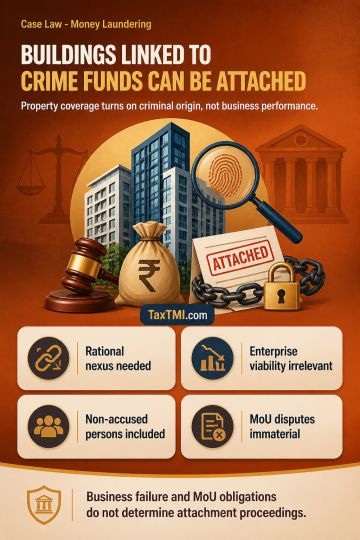
Provisional attachment of proceeds of crime extends to buildings representing criminally derived funds, irrespective of enterprise viability.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Money Laundering September 3, 2026 Case Laws AT
Under the Prevention of Money Laundering Act, provisional attachment may extend to buildings and infrastructure representing the value of proceeds of crime where material establishes a rational nexus between alleged scheduled offences, the generation of criminal proceeds and their use in creating the property. Money-laundering does not depend on the commercial success or failure of the underlying enterprise; the relevant inquiry is whether property was directly or indirectly derived or obtained through criminal activity relating to a scheduled offence. Attachment may apply to persons connected with proceeds of crime even if they are not accused in the scheduled offence. Disputes concerning reciprocal obligations under a memorandum of understanding do not determine attachment proceedings.

Topics

Acts Income Tax