Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Proof of cash receipt is essential before imposing penalties for alleged violations of cash-transaction restrictions.
    Foreign-contribution disclosure mismatches require substantive reconciliation, preventing automatic treatment of separately reported interest income a...
    Business expenditure after branch transfer requires verification of retained assets and related legal expenses before deductibility is determined.
    Enhanced taxation under section 115BBE applies to surrendered excess stock and cash where the amended provision was already operative.
    Statutory sequence for benami attachment invalidates approval obtained before notice to the alleged benamidar, requiring fresh action under law.
    Writ jurisdiction over customs prohibition claims survives alternative remedies where statutory basis and objective legal standards are disputed.
    Statutory limits on provisional attachment require bank accounts to be defrozen when the permitted attachment period expires.
    Transitional protection for restricted gold imports can cover genuine prepaid contracts despite absence of irrevocable commercial letters of credit.
    Reasonable belief for gold seizure governs statutory burden, confiscation, and penalties where smuggling lacks evidentiary support.
    Strict construction of customs exemptions denied concession for brake components, while limitation restricted differential duty to timely Bills of Ent...
    Way Leave Permissions cannot be retrospectively revived through insolvency plans, and affected infrastructure holders require safety review and hearin...
    Interim insolvency moratorium does not halt cheque-dishonour prosecution, preserving negotiable instrument credibility and commercial discipline.
    IBC appeal limitation permits only a narrowly condonable delay, rendering belated challenges to CIRP revival not maintainable.
    Discharge-stage scrutiny requires strong suspicion, not trial-level evidence, where records and statements link accused to money-laundering.
    Recipient-funded renovations lack nexus with renting service and cannot increase taxable rental consideration or support penalties.
    GST enforcement must respect statutory conditions, protect genuine input tax credit claims, and distinguish bona fide errors from fraud.
    Low-value export registration exemption removes RCMC requirements for eligible consignments while higher-value exports remain subject to registration.
    Anti-dumping duty on Calcined Gypsum Powder imports remains effective through 16 March 2027 unless earlier changed.
    Inter-terminal container movement requires customs escort, permit reconciliation, and indemnity, while delayed DPD cargo may move to designated CFS ya...
    Extended GST limitation requires prima facie material linking tax shortfall to fraud, wilful misstatement, or suppression.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Money Laundering

Under the Prevention of Money Laundering Act, provisional...

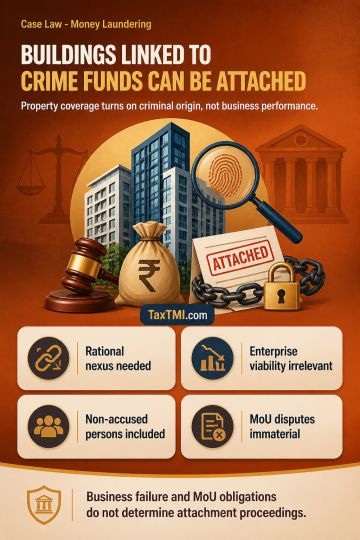
Provisional attachment of proceeds of crime extends to buildings representing criminally derived funds, irrespective of enterprise viability.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Money Laundering September 3, 2026 Case Laws AT
Under the Prevention of Money Laundering Act, provisional attachment may extend to buildings and infrastructure representing the value of proceeds of crime where material establishes a rational nexus between alleged scheduled offences, the generation of criminal proceeds and their use in creating the property. Money-laundering does not depend on the commercial success or failure of the underlying enterprise; the relevant inquiry is whether property was directly or indirectly derived or obtained through criminal activity relating to a scheduled offence. Attachment may apply to persons connected with proceeds of crime even if they are not accused in the scheduled offence. Disputes concerning reciprocal obligations under a memorandum of understanding do not determine attachment proceedings.

Topics

Acts Income Tax