Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
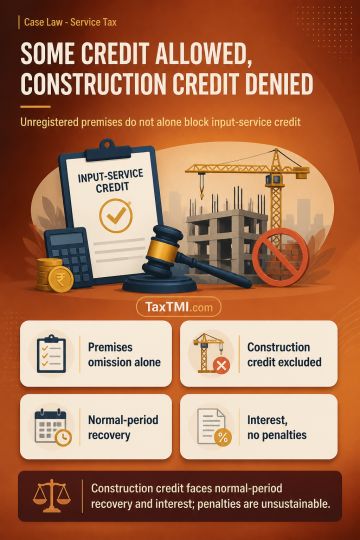
CENVAT credit on input services received at premises omitted from a centralised registration cannot be denied solely because those premises are unregistered. In contrast, works contract services used to construct or set up BPO branches fall within the exclusion for construction of buildings or civil structures, making related credit inadmissible. Where disputed credit was disclosed in ST-3 returns and refund claims, audit detection alone does not establish suppression or other conditions for extended limitation; recovery is confined to the normal period and requires recomputation. Interest follows on recoverable inadmissible credit, but penalties based on suppression or failure to include premises are unsustainable without the requisite contravention or intent to evade.
CENVAT credit on input services received at premises omitted from a centralised registration cannot be denied solely because those premises are unregistered. In contrast, works contract services used to construct or set up BPO branches fall within the exclusion for construction of buildings or civil structures, making related credit inadmissible. Where disputed credit was disclosed in ST-3 returns and refund claims, audit detection alone does not establish suppression or other conditions for extended limitation; recovery is confined to the normal period and requires recomputation. Interest follows on recoverable inadmissible credit, but penalties based on suppression or failure to include premises are unsustainable without the requisite contravention or intent to evade.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886