Reassessment sanction under extended limitation required approval from the competent specified authority, invalidating proceedings approved by an inco...
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
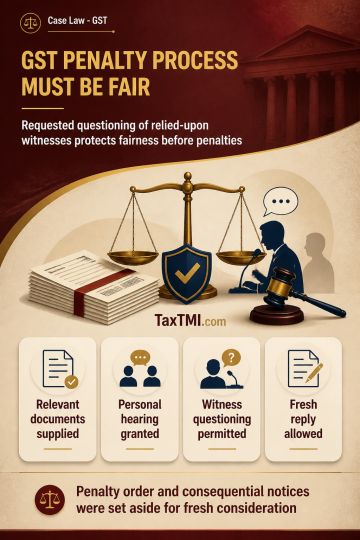
Cross-examination of persons whose statements are relied upon in GST penalty proceedings is necessary to satisfy principles of natural justice where the affected party specifically requests it. Denial of that opportunity before imposing penalty constitutes a serious procedural defect. The penalty order and consequential notices were set aside, with fresh consideration required after supplying relevant documents, granting a personal hearing, permitting cross-examination of relied-upon persons, and allowing a fresh reply. The merits of the underlying allegations remained open for independent reconsideration.
Cross-examination of persons whose statements are relied upon in GST penalty proceedings is necessary to satisfy principles of natural justice where the affected party specifically requests it. Denial of that opportunity before imposing penalty constitutes a serious procedural defect. The penalty order and consequential notices were set aside, with fresh consideration required after supplying relevant documents, granting a personal hearing, permitting cross-examination of relied-upon persons, and allowing a fresh reply. The merits of the underlying allegations remained open for independent reconsideration.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888