Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
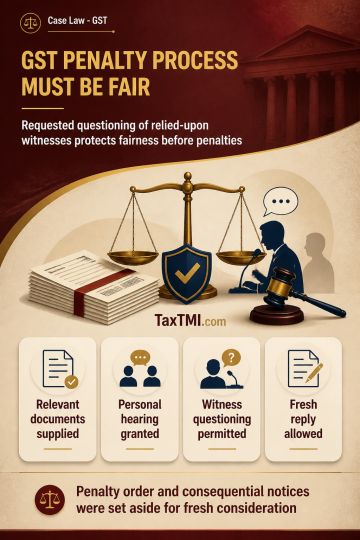
Cross-examination of persons whose statements are relied upon in GST penalty proceedings is necessary to satisfy principles of natural justice where the affected party specifically requests it. Denial of that opportunity before imposing penalty constitutes a serious procedural defect. The penalty order and consequential notices were set aside, with fresh consideration required after supplying relevant documents, granting a personal hearing, permitting cross-examination of relied-upon persons, and allowing a fresh reply. The merits of the underlying allegations remained open for independent reconsideration.
Cross-examination of persons whose statements are relied upon in GST penalty proceedings is necessary to satisfy principles of natural justice where the affected party specifically requests it. Denial of that opportunity before imposing penalty constitutes a serious procedural defect. The penalty order and consequential notices were set aside, with fresh consideration required after supplying relevant documents, granting a personal hearing, permitting cross-examination of relied-upon persons, and allowing a fresh reply. The merits of the underlying allegations remained open for independent reconsideration.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888