Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
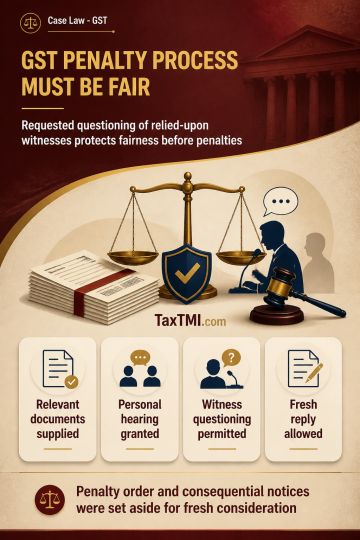
Cross-examination of persons whose statements are relied upon in GST penalty proceedings is necessary to satisfy principles of natural justice where the affected party specifically requests it. Denial of that opportunity before imposing penalty constitutes a serious procedural defect. The penalty order and consequential notices were set aside, with fresh consideration required after supplying relevant documents, granting a personal hearing, permitting cross-examination of relied-upon persons, and allowing a fresh reply. The merits of the underlying allegations remained open for independent reconsideration.
Cross-examination of persons whose statements are relied upon in GST penalty proceedings is necessary to satisfy principles of natural justice where the affected party specifically requests it. Denial of that opportunity before imposing penalty constitutes a serious procedural defect. The penalty order and consequential notices were set aside, with fresh consideration required after supplying relevant documents, granting a personal hearing, permitting cross-examination of relied-upon persons, and allowing a fresh reply. The merits of the underlying allegations remained open for independent reconsideration.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894