Charitable trust registration requires a specified-violation notice; settled cash deposits and related-party payments did not justify cancellation or ...
Page of 4937
Press 'Enter' after typing page number.
2281 to 2300 of 98735 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
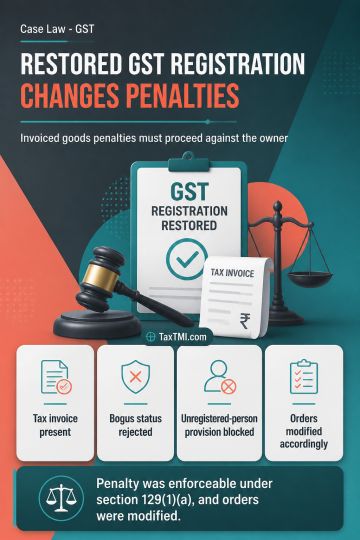
For goods detained while accompanied by a tax invoice, penalty proceedings fall under section 129(1)(a) where the taxpayer can be regarded as the owner of the goods. Subsequent restoration of GST registration prevents treating the consignor or consignee as bogus or maintaining proceedings under section 129(1)(b) on the basis that the taxpayer was unregistered. The penalty was therefore enforceable under section 129(1)(a), and the orders were modified accordingly.
For goods detained while accompanied by a tax invoice, penalty proceedings fall under section 129(1)(a) where the taxpayer can be regarded as the owner of the goods. Subsequent restoration of GST registration prevents treating the consignor or consignee as bogus or maintaining proceedings under section 129(1)(b) on the basis that the taxpayer was unregistered. The penalty was therefore enforceable under section 129(1)(a), and the orders were modified accordingly.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937