Charitable trust registration requires a specified-violation notice; settled cash deposits and related-party payments did not justify cancellation or ...
Page of 4935
Press 'Enter' after typing page number.
2241 to 2260 of 98695 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
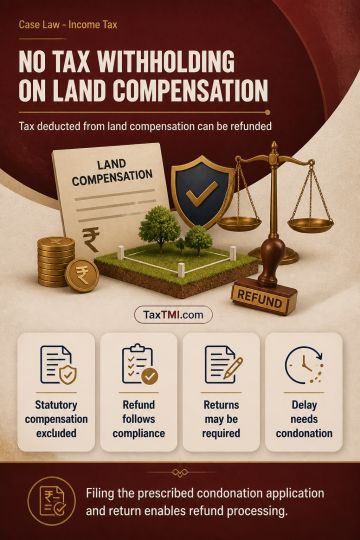
Compensation payable to land losers under the Right to Fair Compensation and Transparency in Land Acquisition, Rehabilitation and Resettlement Act, 2013 is not subject to income-tax deduction or payment. Tax deducted at source from such compensation is refundable. Where a refund claim is affected by non-filing of the return or delay, the prescribed condonation application and return must be filed to enable processing of the refund. The stated position treats the statutory land-acquisition compensation as outside the scope of taxable income for TDS purposes.
Compensation payable to land losers under the Right to Fair Compensation and Transparency in Land Acquisition, Rehabilitation and Resettlement Act, 2013 is not subject to income-tax deduction or payment. Tax deducted at source from such compensation is refundable. Where a refund claim is affected by non-filing of the return or delay, the prescribed condonation application and return must be filed to enable processing of the refund. The stated position treats the statutory land-acquisition compensation as outside the scope of taxable income for TDS purposes.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935