Commodity derivatives position limits adopt revised breach penalties, broad commodity criteria, and client open-position limits based on deliverable s...
Effective hearing in GST adjudication requires actual opportunity to respond; ineffective service through a former auditor invalidated ex parte procee...
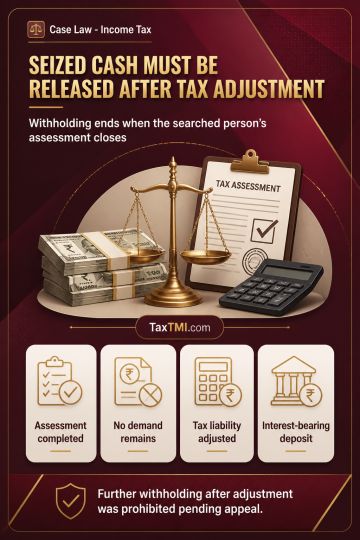
Retention of seized cash under Section 132B cannot continue after completion of the searched person's assessment where no demand remains against that person. Subsequent reassessment proceedings against a non-searched assessee, without a warrant of authorisation, do not permit continued withholding of cash accepted as belonging to that assessee. The cash must be released after adjustment against the assessee's tax liability. Interest calculated on the amount must remain in an interest-bearing deposit pending determination of entitlement to interest by a Larger Bench. Pending disposal of the appeal, retention beyond tax adjustment was prohibited.
Retention of seized cash under Section 132B cannot continue after completion of the searched person's assessment where no demand remains against that person. Subsequent reassessment proceedings against a non-searched assessee, without a warrant of authorisation, do not permit continued withholding of cash accepted as belonging to that assessee. The cash must be released after adjustment against the assessee's tax liability. Interest calculated on the amount must remain in an interest-bearing deposit pending determination of entitlement to interest by a Larger Bench. Pending disposal of the appeal, retention beyond tax adjustment was prohibited.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI

 of 4949




 Get Daily Updates