Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adju...
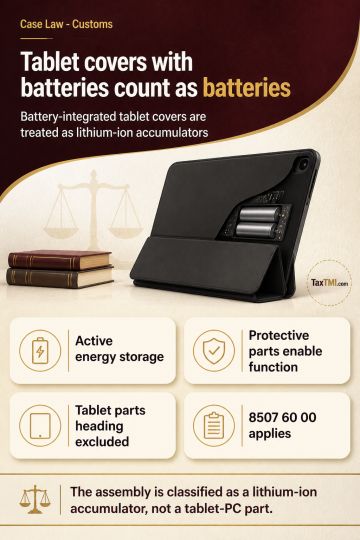
Battery-integrated tablet rear covers classify as lithium-ion accumulators when protective components enable the battery's active energy-storage funct...
Page of 4932
Press 'Enter' after typing page number.
1701 to 1720 of 98625 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Tax deduction at source under section 194C applies to External...
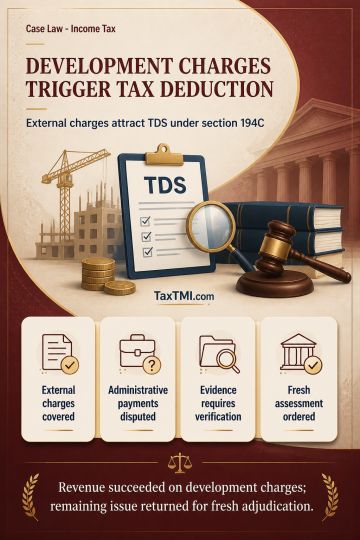
External development charges trigger TDS under section 194C, while disputed administrative payments require factual verification and fresh adjudication.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Tax deduction at source under section 194C applies to External Development Charges paid to the urban development authority, rendering the payer liable for non-deduction, subject to the pending Supreme Court proceedings. Payments later characterised as administrative charges for changes in beneficial interest and development rights require verification of the supporting evidence, the applicable State scheme, the payments' nature, and any resulting obligations under Chapter XVII-B. Those disputed payments require de novo determination by the Assessing Officer after admission of evidence and an adequate hearing. The Revenue's position succeeded on External Development Charges, while the remaining TDS issue was restored for fresh adjudication.
Tax deduction at source under section 194C applies to External Development Charges paid to the urban development authority, rendering the payer liable for non-deduction, subject to the pending Supreme Court proceedings. Payments later characterised as administrative charges for changes in beneficial interest and development rights require verification of the supporting evidence, the applicable State scheme, the payments' nature, and any resulting obligations under Chapter XVII-B. Those disputed payments require de novo determination by the Assessing Officer after admission of evidence and an adequate hearing. The Revenue's position succeeded on External Development Charges, while the remaining TDS issue was restored for fresh adjudication.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932