Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
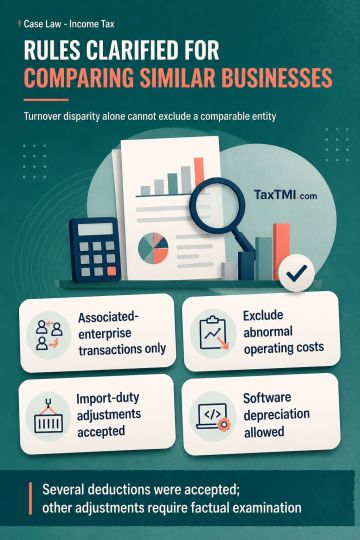
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
Page of 4929
Press 'Enter' after typing page number.
1761 to 1780 of 98580 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Negative liens over participating interests in oil and gas...
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expansion capacity.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Negative liens over participating interests in oil and gas blocks and related receivables, created to secure associated enterprises' borrowings, are treated as international transactions where they restrict the asset-owning entity's ability to charge, borrow against, or expand using its operating assets. A lender's security interest may continue despite the borrower entities' bankruptcy. Arm's-length pricing must reflect the negative lien's factual character and resulting impairment of borrowing capacity; averaging bank-guarantee rates or applying loan-benchmarking approaches is not appropriate. The arm's-length price requires fresh determination under applicable transfer-pricing provisions.
Negative liens over participating interests in oil and gas blocks and related receivables, created to secure associated enterprises' borrowings, are treated as international transactions where they restrict the asset-owning entity's ability to charge, borrow against, or expand using its operating assets. A lender's security interest may continue despite the borrower entities' bankruptcy. Arm's-length pricing must reflect the negative lien's factual character and resulting impairment of borrowing capacity; averaging bank-guarantee rates or applying loan-benchmarking approaches is not appropriate. The arm's-length price requires fresh determination under applicable transfer-pricing provisions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929