Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
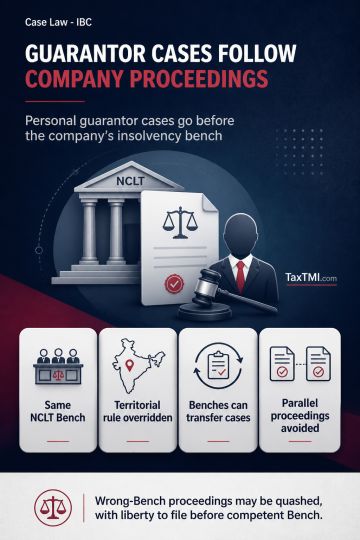
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
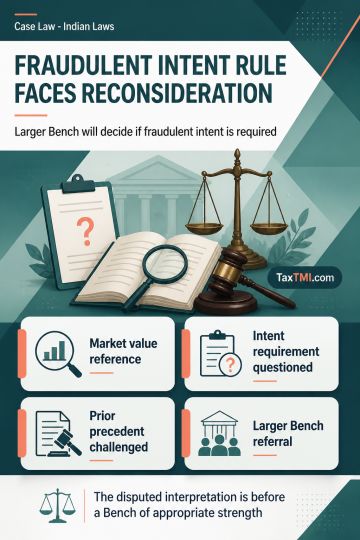
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
Section 90(2) permits a taxpayer to elect the more beneficial treatment available under domestic tax law or the India-Mauritius DTAA; treaty treatment cannot be imposed where the domestic-law position is more favourable. This principle supports setting off current and brought-forward long-term capital losses on shares acquired before 1 April 2017 against taxable capital gains from shares acquired thereafter. The claimed losses are to be considered in recomputing taxable income where the taxpayer validly exercises the beneficial statutory option.
Section 90(2) permits a taxpayer to elect the more beneficial treatment available under domestic tax law or the India-Mauritius DTAA; treaty treatment cannot be imposed where the domestic-law position is more favourable. This principle supports setting off current and brought-forward long-term capital losses on shares acquired before 1 April 2017 against taxable capital gains from shares acquired thereafter. The claimed losses are to be considered in recomputing taxable income where the taxpayer validly exercises the beneficial statutory option.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4934