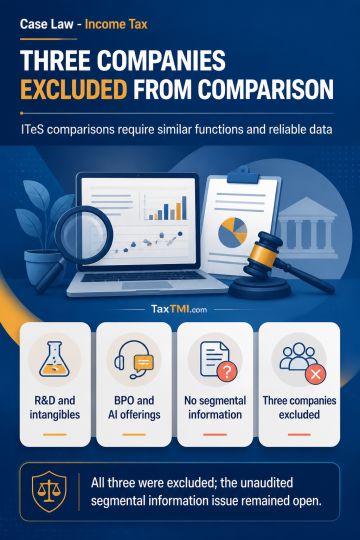
Functional comparability under TNMM supported exclusion of ITeS comparables with R&D, intangibles, diversified operations, or unavailable segmental da...
Page of 4893
Press 'Enter' after typing page number.
1521 to 1540 of 97857 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Section 90(2) permits a taxpayer to elect the more beneficial treatment available under domestic tax law or the India-Mauritius DTAA; treaty treatment cannot be imposed where the domestic-law position is more favourable. This principle supports setting off current and brought-forward long-term capital losses on shares acquired before 1 April 2017 against taxable capital gains from shares acquired thereafter. The claimed losses are to be considered in recomputing taxable income where the taxpayer validly exercises the beneficial statutory option.
Section 90(2) permits a taxpayer to elect the more beneficial treatment available under domestic tax law or the India-Mauritius DTAA; treaty treatment cannot be imposed where the domestic-law position is more favourable. This principle supports setting off current and brought-forward long-term capital losses on shares acquired before 1 April 2017 against taxable capital gains from shares acquired thereafter. The claimed losses are to be considered in recomputing taxable income where the taxpayer validly exercises the beneficial statutory option.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4893