Withdrawal of obsolete FEMA circulars streamlines rules on external commercial borrowings, non-resident bond investments, and money transfer sub-agent...
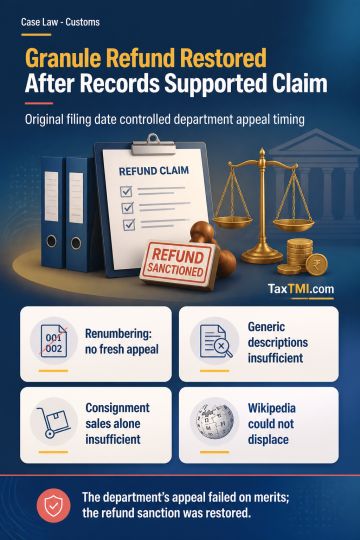
Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
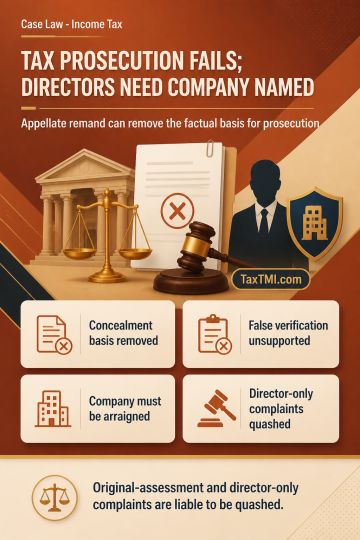
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Page of 4935
Press 'Enter' after typing page number.
1961 to 1980 of 98695 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
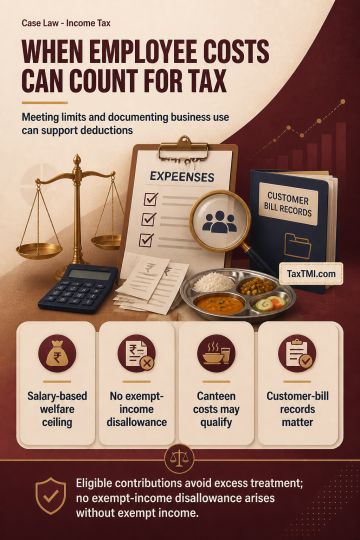
Welfare-fund contribution deductibility depends on comparing the employer's contribution with gross salary, rather than figures distorted by separate accounting of net salaries and combined employee-employer PF and ESI payments. Contributions remaining within the prescribed ceiling are not treated as excess. Disallowance of expenditure relating to exempt income under section 14A read with rule 8D does not arise where no exempt income is earned. Amounts recovered through customer service bills for canteen and transportation facilities used by deputed employees may qualify as business expenditure when incurred wholly and exclusively for the business and supported by customer-bill records.
Welfare-fund contribution deductibility depends on comparing the employer's contribution with gross salary, rather than figures distorted by separate accounting of net salaries and combined employee-employer PF and ESI payments. Contributions remaining within the prescribed ceiling are not treated as excess. Disallowance of expenditure relating to exempt income under section 14A read with rule 8D does not arise where no exempt income is earned. Amounts recovered through customer service bills for canteen and transportation facilities used by deputed employees may qualify as business expenditure when incurred wholly and exclusively for the business and supported by customer-bill records.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935