Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
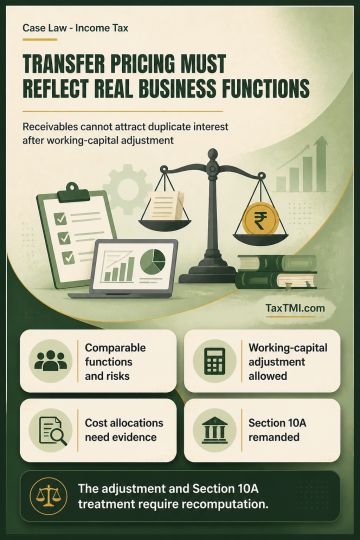
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
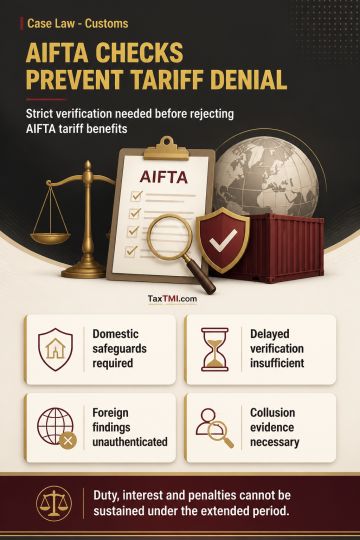
AIFTA Certificates of Origin may be rejected only through compliance with the domestic verification safeguards in Rules 7(c) and 7(d); suspected fraud does not remove those requirements under Rule 23. Delayed, partial verification and an unauthenticated foreign finding of non-authenticity, without origin test reports, signature evidence or authenticated underlying material, do not establish fraudulent origin or justify denial of preferential tariff treatment. Extended limitation for customs recovery requires proof of the importer's positive collusion, wilful misstatement or suppression, including conscious participation in certificate falsification. Non-culpatory statements and absent evidence of knowledge or fraud do not sustain duty, interest or penalties under the extended period.
AIFTA Certificates of Origin may be rejected only through compliance with the domestic verification safeguards in Rules 7(c) and 7(d); suspected fraud does not remove those requirements under Rule 23. Delayed, partial verification and an unauthenticated foreign finding of non-authenticity, without origin test reports, signature evidence or authenticated underlying material, do not establish fraudulent origin or justify denial of preferential tariff treatment. Extended limitation for customs recovery requires proof of the importer's positive collusion, wilful misstatement or suppression, including conscious participation in certificate falsification. Non-culpatory statements and absent evidence of knowledge or fraud do not sustain duty, interest or penalties under the extended period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4939