Fraudulent import documents suspend limitation protection, while redemption of confiscated goods requires duty and interest despite bona fide purchase...
ODR arbitration participation remains mandatory after failed conciliation, while jurisdictional and maintainability objections stay available before t...
Transparency in technical bid evaluation requires disclosed standards and recorded reasons; opaque scoring invalidated tender awards and required fres...
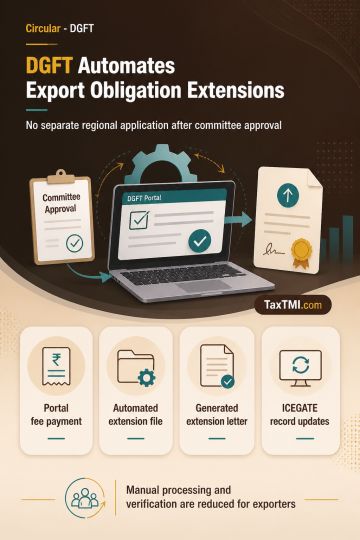
Automated export obligation extensions remove separate regional applications after committee approval for Advance Authorisation and EPCG authorisation...
International cargo transhipment through Indian ports continues with Customs-controlled storage, re-export safeguards, and coordinated multi-station m...
Excise assessment of superior kerosene oil is determined by its form and exemption eligibility at factory removal. Kerosene cleared for sale through the Public Distribution System after satisfying exemption conditions does not become assessable at motor-spirit or high-speed-diesel rates merely because it later forms a pipeline interface beyond the refinery; an administrative circular cannot create liability contrary to governing provisions. The differential-duty demand on interface kerosene was therefore unsustainable. Extended limitation requires evidence of suppression or wilful misstatement with intent to evade duty; departmental ability to inquire and a bona fide belief defeated its use. Without such evidence, penalties against the entities and employee were not imposable.
Excise assessment of superior kerosene oil is determined by its form and exemption eligibility at factory removal. Kerosene cleared for sale through the Public Distribution System after satisfying exemption conditions does not become assessable at motor-spirit or high-speed-diesel rates merely because it later forms a pipeline interface beyond the refinery; an administrative circular cannot create liability contrary to governing provisions. The differential-duty demand on interface kerosene was therefore unsustainable. Extended limitation requires evidence of suppression or wilful misstatement with intent to evade duty; departmental ability to inquire and a bona fide belief defeated its use. Without such evidence, penalties against the entities and employee were not imposable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896