Alternative statutory remedy and unexplained delay barred writ review of customs confiscation adjudication, leaving merits for appellate consideration...
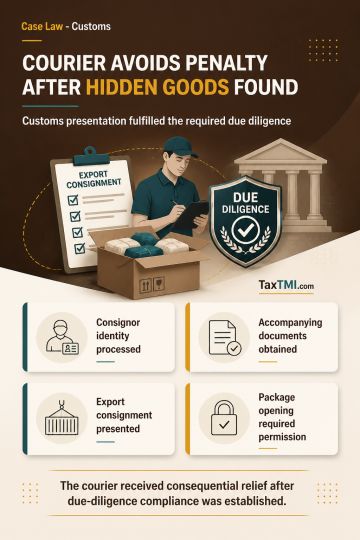
Authorised courier due diligence protects against penalties where declared exports conceal prohibited goods despite proper documentation and customs p...
Inadvertent payment of GST under the IGST head, where CGST and SGST were actually payable and no IGST liability existed, is treated as a clerical error rather than a payment made under a misconception that the supply was inter-State. Section 77(2) therefore does not apply. Where the full GST liability has effectively been discharged, interest and penalty are not payable. The amount remitted as IGST may be appropriated against the CGST and SGST liability; where procedurally required, refund and transfer of the amount may be sought.
Inadvertent payment of GST under the IGST head, where CGST and SGST were actually payable and no IGST liability existed, is treated as a clerical error rather than a payment made under a misconception that the supply was inter-State. Section 77(2) therefore does not apply. Where the full GST liability has effectively been discharged, interest and penalty are not payable. The amount remitted as IGST may be appropriated against the CGST and SGST liability; where procedurally required, refund and transfer of the amount may be sought.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886