Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Page of 4915
Press 'Enter' after typing page number.
21 to 40 of 98291 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
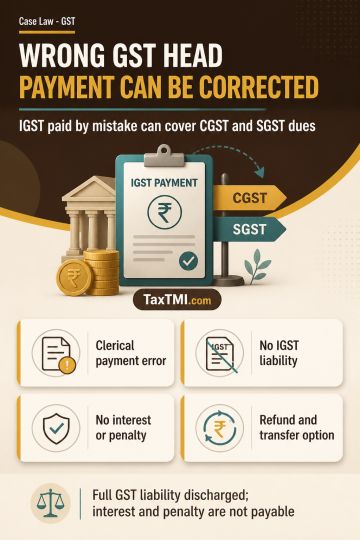
Inadvertent payment of GST under the IGST head, where CGST and SGST were actually payable and no IGST liability existed, is treated as a clerical error rather than a payment made under a misconception that the supply was inter-State. Section 77(2) therefore does not apply. Where the full GST liability has effectively been discharged, interest and penalty are not payable. The amount remitted as IGST may be appropriated against the CGST and SGST liability; where procedurally required, refund and transfer of the amount may be sought.
Inadvertent payment of GST under the IGST head, where CGST and SGST were actually payable and no IGST liability existed, is treated as a clerical error rather than a payment made under a misconception that the supply was inter-State. Section 77(2) therefore does not apply. Where the full GST liability has effectively been discharged, interest and penalty are not payable. The amount remitted as IGST may be appropriated against the CGST and SGST liability; where procedurally required, refund and transfer of the amount may be sought.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915