External development charges trigger TDS under section 194C, while disputed administrative payments require factual verification and fresh adjudicatio...
Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
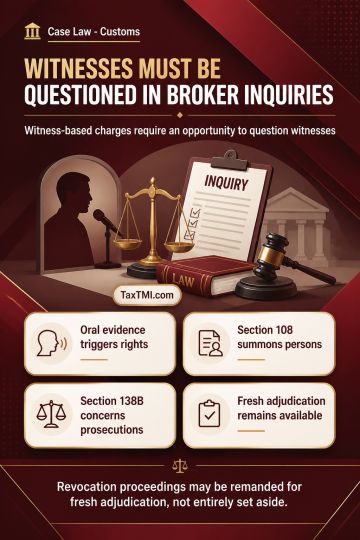
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
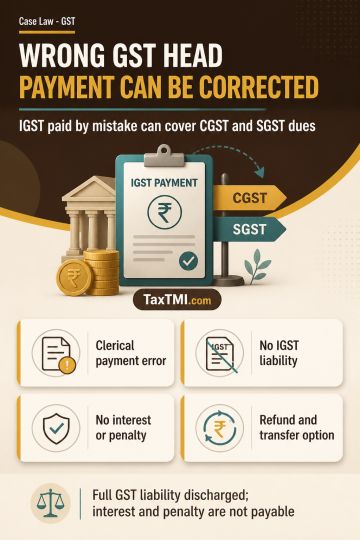
Inadvertent payment of GST under the IGST head, where CGST and SGST were actually payable and no IGST liability existed, is treated as a clerical error rather than a payment made under a misconception that the supply was inter-State. Section 77(2) therefore does not apply. Where the full GST liability has effectively been discharged, interest and penalty are not payable. The amount remitted as IGST may be appropriated against the CGST and SGST liability; where procedurally required, refund and transfer of the amount may be sought.
Inadvertent payment of GST under the IGST head, where CGST and SGST were actually payable and no IGST liability existed, is treated as a clerical error rather than a payment made under a misconception that the supply was inter-State. Section 77(2) therefore does not apply. Where the full GST liability has effectively been discharged, interest and penalty are not payable. The amount remitted as IGST may be appropriated against the CGST and SGST liability; where procedurally required, refund and transfer of the amount may be sought.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937