Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
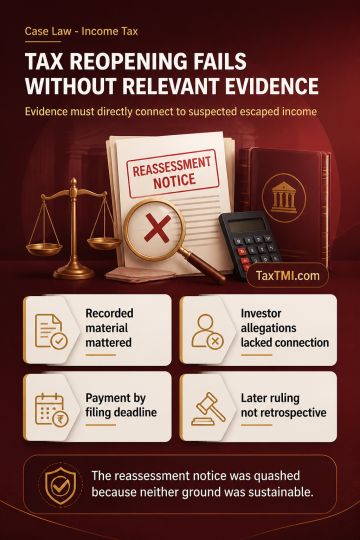
Reassessment requires recorded material to have a rational connection and live nexus with the belief that income escaped assessment; suspicion based on statements or survey material unrelated to the taxpayer or investment transaction is insufficient. Allegations concerning an investor's representative, without transaction-specific material, could not support reopening for purportedly non-genuine share capital and share premium. For employees' provident fund and insurance contributions, the law prevailing when notice was issued allowed deduction where payment was made by the return-filing due date. A later contrary Supreme Court ruling could not retrospectively validate the recorded reason. The reassessment notice was quashed because neither ground established a sustainable reason to believe.
Reassessment requires recorded material to have a rational connection and live nexus with the belief that income escaped assessment; suspicion based on statements or survey material unrelated to the taxpayer or investment transaction is insufficient. Allegations concerning an investor's representative, without transaction-specific material, could not support reopening for purportedly non-genuine share capital and share premium. For employees' provident fund and insurance contributions, the law prevailing when notice was issued allowed deduction where payment was made by the return-filing due date. A later contrary Supreme Court ruling could not retrospectively validate the recorded reason. The reassessment notice was quashed because neither ground established a sustainable reason to believe.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918