Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
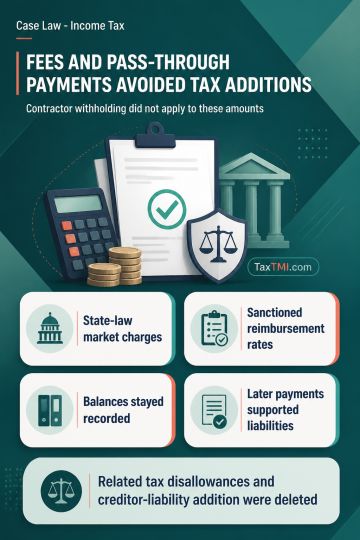
Market fee and cess payable under a State enactment are statutory levies, not consideration for contractual work, and therefore do not attract tax deduction at source under the provision governing contractual payments. Government-prescribed procurement payments to societies, supported by sanctioned rates, reimbursement arrangements, control accounts and separately identifiable remuneration, constitute pass-through disbursements rather than contractor or subcontractor expenditure. The related disallowances for non-deduction of tax were deleted. Remission or cessation of a trading liability requires proof of a benefit obtained through an actual waiver, write-back, remission or extinguishment during the relevant year. Outstanding balances, without more, do not establish cessation where liabilities remain recorded, transactions continue and subsequent payments occur; the creditor-liability addition was deleted.
Market fee and cess payable under a State enactment are statutory levies, not consideration for contractual work, and therefore do not attract tax deduction at source under the provision governing contractual payments. Government-prescribed procurement payments to societies, supported by sanctioned rates, reimbursement arrangements, control accounts and separately identifiable remuneration, constitute pass-through disbursements rather than contractor or subcontractor expenditure. The related disallowances for non-deduction of tax were deleted. Remission or cessation of a trading liability requires proof of a benefit obtained through an actual waiver, write-back, remission or extinguishment during the relevant year. Outstanding balances, without more, do not establish cessation where liabilities remain recorded, transactions continue and subsequent payments occur; the creditor-liability addition was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918