GST payment representations require record-based, reasoned decisions while substantive entitlement remains open for determination by competent authori...
Reassessment sanction under extended limitation required approval from the competent specified authority, invalidating proceedings approved by an inco...
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
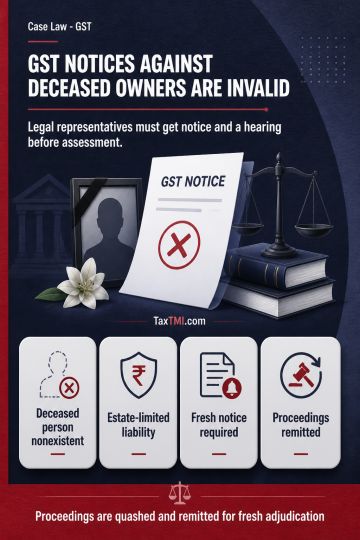
Show cause notices issued in the name of a deceased taxable person are void because tax cannot be determined against a non-existent person. Although legal representatives are liable only to the extent of the deceased's estate, that liability requires assessment against them in their representative capacity. They must receive a fresh notice and a meaningful opportunity to reply and be heard before liability is determined. Proceedings initiated solely against a deceased proprietor, including adjudication and recovery, are liable to be quashed and remitted for fresh adjudication against the legal representatives without determination on merits.
Show cause notices issued in the name of a deceased taxable person are void because tax cannot be determined against a non-existent person. Although legal representatives are liable only to the extent of the deceased's estate, that liability requires assessment against them in their representative capacity. They must receive a fresh notice and a meaningful opportunity to reply and be heard before liability is determined. Proceedings initiated solely against a deceased proprietor, including adjudication and recovery, are liable to be quashed and remitted for fresh adjudication against the legal representatives without determination on merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888