Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
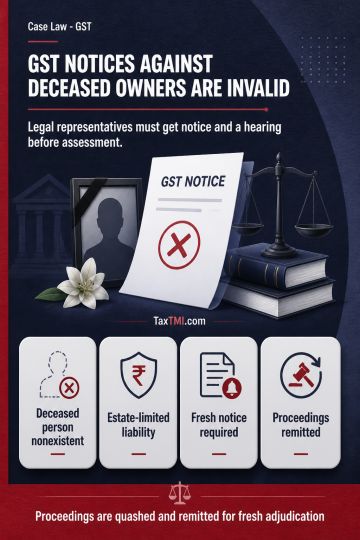
Show cause notices issued in the name of a deceased taxable person are void because tax cannot be determined against a non-existent person. Although legal representatives are liable only to the extent of the deceased's estate, that liability requires assessment against them in their representative capacity. They must receive a fresh notice and a meaningful opportunity to reply and be heard before liability is determined. Proceedings initiated solely against a deceased proprietor, including adjudication and recovery, are liable to be quashed and remitted for fresh adjudication against the legal representatives without determination on merits.
Show cause notices issued in the name of a deceased taxable person are void because tax cannot be determined against a non-existent person. Although legal representatives are liable only to the extent of the deceased's estate, that liability requires assessment against them in their representative capacity. They must receive a fresh notice and a meaningful opportunity to reply and be heard before liability is determined. Proceedings initiated solely against a deceased proprietor, including adjudication and recovery, are liable to be quashed and remitted for fresh adjudication against the legal representatives without determination on merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894