Transfer-pricing comparability requires exclusion of financially illogical super-profit comparables and correction of unsupported annual-report and ma...
Charitable character assessment preserves Section 80G approval despite inclusive spiritual teachings and incidental religious expenditure within the s...
Penalty proceedings for cash-loan acceptance require assessment proceedings and recorded Assessing Officer satisfaction; absent these, the proceedings...
Functional comparability governs software-service benchmarking: dissimilar companies are excluded, while related-party filters, margins and working-ca...
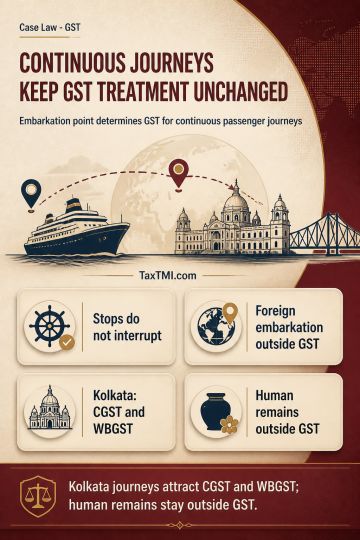
Passenger transportation follows the place of embarkation for a continuous journey. Where either the supplier or passenger is outside India, a short transit stop does not amount to a stopover or interrupt the journey; transportation embarking outside India consequently has a place of supply outside India and is not subject to GST. Where both supplier and passenger are in India, embarkation from Kolkata makes the service an intra-State supply liable to CGST and WBGST at the notified rate, with economy-class treatment subject to the input tax credit condition. Air transportation of human remains falls within funeral, burial, crematorium or mortuary services and is neither a supply of goods nor services, so remains outside GST.
Passenger transportation follows the place of embarkation for a continuous journey. Where either the supplier or passenger is outside India, a short transit stop does not amount to a stopover or interrupt the journey; transportation embarking outside India consequently has a place of supply outside India and is not subject to GST. Where both supplier and passenger are in India, embarkation from Kolkata makes the service an intra-State supply liable to CGST and WBGST at the notified rate, with economy-class treatment subject to the input tax credit condition. Air transportation of human remains falls within funeral, burial, crematorium or mortuary services and is neither a supply of goods nor services, so remains outside GST.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891